
DailyPay On-Demand Pay
- Rating
- 4.7
- Downloads
- 1.00M
- Content Rating
- Everyone
DailyPay On-Demand Pay - Screenshots
Pros
- Access earned wages before your regular payday.
- Can help cover unexpected expenses without using a credit card.
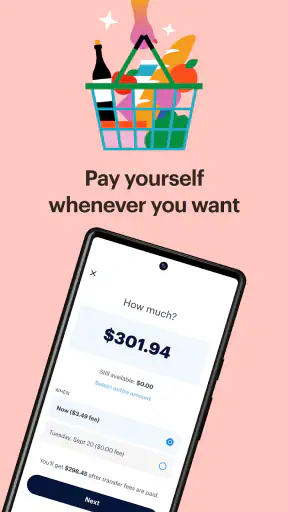
- Transfers are available through a mobile app.
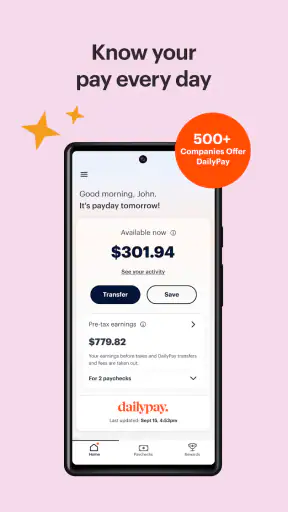
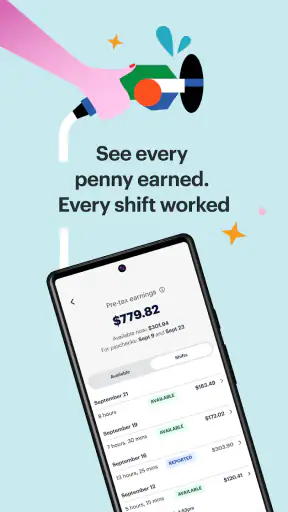
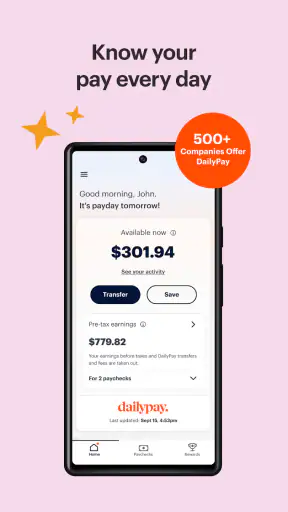
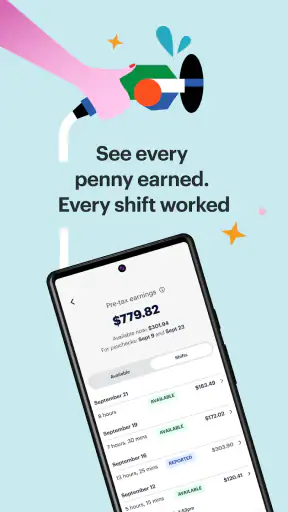
- Clear view of available earnings and transaction activity.
- Useful budgeting support for workers with variable cash flow.
Cons
- Availability depends on employer participation and eligibility.
- Transfer fees may apply
- depending on the delivery option.
- Not all earned wages may be available for early access.
- Frequent use can make it harder to manage payday income.
- Account and payout issues may require employer or support assistance.
DailyPay On-Demand Pay - Description
- App Name
- DailyPay On-Demand Pay
- Package Name
- com.DailyPay.DailyPay
- Developer
- DailyPay Inc
- Category
- Finance
- Last Updated
- Dec 7, 2018
- Version
- 52.0.0
I approached DailyPay On-Demand Pay as a practical finance app rather than a general budgeting tool. Its purpose is simple: it can let eligible workers access wages they have already earned before the normal payday. That distinction matters. This is not an app for growing savings, investing spare cash, or replacing a bank account. It is designed around timing, giving you a way to deal with a bill or everyday expense when your work has already generated income but your paycheck has not arrived yet.
In my experience, that narrow focus is both its strongest quality and its biggest limitation. When the problem is a short gap between earning money and needing to spend it, the idea is easy to understand. When the real problem is that monthly expenses are consistently higher than income, early wage access only moves the pressure around. I would recommend looking at DailyPay with that difference in mind before treating it as a general financial solution.
How DailyPay On-Demand Pay fits into everyday finances
DailyPay Inc develops the app, which is available free of charge and carries an Everyone age rating. It belongs in the finance category, but I would place it in a very specific corner of that category: earned-wage access. The app is useful only in the context of participating employment arrangements, so downloading it is not the same as automatically gaining access to wages from any job.
The first practical question is therefore not “How much can I withdraw?” but “Does my employer and work arrangement support DailyPay?” That eligibility check should come before building a budget around the service. If your workplace is not connected to the platform, the app cannot turn an unrelated job into an on-demand pay source. This is an important difference from a conventional banking app, where opening an account generally gives you access to the bank’s own services regardless of employer.
For someone who is eligible, the useful scenario is easy to picture. Imagine that I have worked several shifts, but a utility bill is due before the scheduled paycheck. I may prefer to access part of the wages already earned rather than use a credit card or incur a late fee. DailyPay can fit that moment because it addresses the timing issue directly. I would still check the amount available, the delivery choice shown in the app, and the effect on my next paycheck before confirming anything.
The key habit is to treat early access as a timing tool, not extra income. Money received today is money that will not arrive in the usual paycheck later. Keeping that mental separation prevents one of the easiest mistakes: spending the available balance as though it were an addition to the month’s earnings.
The current experience and what the numbers suggest
The app has a 4.7 average from around 238 thousand ratings and more than a million installs. Those figures suggest that DailyPay has reached a substantial audience and that many users find the basic idea valuable. They do not guarantee that every employer, payroll arrangement, or personal situation will work equally well, so I would use the rating as a sign of broad usefulness rather than a promise of effortless access.
DailyPay was released on December 7, 2018, and the current version is 52.0.0. That history helps explain why the app feels like an established service rather than a newly launched experiment. At the same time, a mature version number should not be confused with a guarantee that every part of the experience will be smooth for every user. Finance apps depend on payroll information and employment setup, so some of the most important parts of the experience sit outside the phone itself.
When I assess an app like this, I pay attention to the handoff between the app and the next paycheck. The most useful information is not just the amount that appears as available. I also want to understand what remains for the regular payday, whether an action is still processing, and whether I am making a one-time choice or creating a habit. A clear balance view is helpful, but personal discipline remains necessary because early access can make the next pay period feel unexpectedly tight.
What the app does better than waiting for payday
The obvious advantage is speed of access to earned wages. Traditional payroll follows a fixed schedule, which works well when bills and income line up. Real life is less tidy. A car repair, a prescription, or a small gap between rent and payday can create a problem even when the money has already been earned. DailyPay addresses that mismatch more directly than a standard checking account does.
Compared with a credit card, using earned wages may feel more transparent because the source of the money is your work rather than borrowed credit. However, I would not assume that early wage access is automatically free or always the cheapest choice. Before confirming a transfer, I would read the in-app terms for the delivery option and compare the total cost with a late fee, a bank overdraft, or another available alternative. The correct choice depends on the situation, not on the label attached to the product.
Compared with a traditional payday loan, the concept is also different because it is connected to wages already earned rather than a separate promise to repay a lender. That does not mean I would use it casually. The practical trade-off is still real: solving today’s shortage can reduce the amount available on the normal payday. For recurring shortfalls, a spending review or a conversation about pay scheduling may be more useful than repeated withdrawals.
A workflow I would use before requesting money
I would start by checking the available amount against the exact expense, rather than taking the maximum simply because it is displayed. If the bill is smaller than the available balance, withdrawing only what is needed reduces the chance of making the next paycheck unnecessarily uncomfortable. This is a small decision, but it turns the app from an impulse button into a controlled cash-flow tool.
Next, I would record the withdrawal in the same place where I track bills. That could be a personal spreadsheet, a notes app, or a paper budget. The point is to make the upcoming reduction visible before payday. This step is especially useful for people who manage several small expenses, because each individual withdrawal can look harmless while the combined effect becomes significant.
I would also avoid using early access for purchases that can wait. A delayed subscription renewal and an urgent transport problem should not receive the same treatment. DailyPay is most convincing when it prevents a concrete consequence, such as a missed essential payment, rather than when it simply makes discretionary spending feel more comfortable for a few days.
One less obvious trade-off is convenience versus attention. The easier it becomes to access money, the less friction there is to reconsider whether the expense is necessary. I see that as a reason to create a personal rule before using the app: reserve it for planned essentials or genuine timing emergencies, and review the next paycheck after every request.
How existing users may experience version 52.0.0
For an existing user, the current version number indicates an actively maintained product line, but I would separate that observation from assumptions about specific new functions. Without a clearly stated change list, it would be unfair to claim that a particular screen, transfer method, or payroll feature was added in this release. What I can say is that users should keep the app updated and pay attention to the wording shown during a transaction, because the live experience is more important than a version label alone.
Updates in a finance app can affect small but important details: how balances are presented, how a request is confirmed, or how an in-progress action is explained. My advice is to slow down after an update rather than relying entirely on muscle memory. Check the destination, the amount, and the expected impact on the next paycheck each time. That habit is sensible even when the interface looks familiar.
New users should expect the first useful moment to depend on setup and eligibility, not merely installation. Existing users should likewise remember that a change in employer, payroll arrangement, or employment status can affect the experience. The app is part of a larger payroll relationship, so a problem may require checking both the app and the workplace process instead of repeatedly tapping the same request button.
Where the experience still has friction
The biggest limitation is that DailyPay cannot solve an income problem by itself. If I regularly need early access to make it through the month, the app may be helping me cope while leaving the underlying budget unchanged. In that situation, I would compare recurring withdrawals with a revised bill schedule, a smaller fixed expense, or a conversation about financial support. The app can smooth timing, but it cannot make an unaffordable pattern affordable.
There is also a psychological cost to splitting one paycheck into several moments. A normal payday creates a clear point at which income arrives. Early access can make money feel continuously available, which may be convenient but can make it harder to see the full monthly picture. I would be cautious if I already find it difficult to track irregular spending or remember automatic payments.
Another point of friction is the dependence on employment eligibility. Someone looking for a universal emergency-funds app may be disappointed because DailyPay is not a substitute for a savings account. Someone who changes jobs frequently should also avoid assuming that access will transfer automatically. I would confirm the current employment connection before relying on the service for a time-sensitive payment.
Finally, the free app label should not end the cost comparison. The app itself may be free to download, but a particular access or delivery choice can have its own terms. I would read the confirmation screen carefully and compare alternatives, especially when the amount is small enough that a fee could represent a meaningful share of the transaction.
Who should use it, and who should look elsewhere
I think DailyPay is a strong fit for an eligible worker with predictable earnings, a temporary cash-flow mismatch, and a clear plan for repaying the timing gap through the next paycheck. It can be particularly practical when the alternative is a late payment or expensive short-term borrowing. The strongest users are not necessarily those who need the most money; they are the people who can identify a specific need and stop once that need is covered.
I would be more cautious recommending it to someone with unstable income, frequent overdrafts, or no way to track upcoming deductions. I would also point people toward a standard savings tool if their main goal is building an emergency reserve, and toward a budgeting app if the main need is understanding spending categories. A bank account is better for everyday deposits and payments; DailyPay is better viewed as a bridge between work already completed and the scheduled payday.
That comparison is important because convenience can disguise a mismatch. If the goal is to save, early wage access may work against that goal by making earned money easier to spend immediately. If the goal is to borrow over a longer period, the app may not be the right product either. I would choose it for short timing problems, not for financing a large purchase or covering a persistent monthly deficit.
Questions I would answer before depending on it
A reader may reasonably ask whether installing the app guarantees access. It does not. The practical starting point is confirming that the employer and employment setup are supported. I would do that before counting an expected early payment in a bill plan.
Another common question is whether using it changes the total amount earned. The important budgeting principle is that early access changes when part of the money arrives, not the basic fact that the money comes from wages already earned. I would therefore write down the amount immediately and treat the regular paycheck as already reduced by that decision.
People also want to know whether it replaces a bank account. In my view, it does not. It is a focused finance app for wage timing, while a bank account handles broader daily money management. Keeping those roles separate makes the product easier to understand and reduces the temptation to use it for tasks it was not designed to handle.
For anyone wondering whether it is suitable for an emergency, I would say it can be useful for a small, immediate need when eligibility and the displayed terms make sense. I would not treat it as a complete emergency plan. A cash reserve remains more flexible because it does not depend on a current employer connection or reduce a future paycheck.
The final question is whether a high rating means it will work perfectly for one person. I would not read it that way. The rating and large user base show that the central service resonates with many people, but payroll timing, employer participation, personal budgeting, and transaction terms still determine the individual result.
What I would watch as the app develops
With version 52.0.0 as the current release, I would watch for improvements that make the financial consequences of early access even easier to understand. The most valuable progress would be clearer explanations around available wages, upcoming payday impact, transaction status, and any cost associated with the selected option. In a finance app, clarity is more important to me than adding decorative features.
I would also look for practical tools that help users stop relying on early access automatically. A useful direction would be stronger visibility into repeated withdrawals and better context around the next paycheck, provided those details are presented plainly. The goal should not be to encourage more frequent use; it should be to help people make an informed choice each time.
For current users, my advice is simple: keep the app updated, read each confirmation carefully, and review the next paycheck after using the service. For new users, confirm eligibility first, start with a small and necessary expense, and compare the displayed terms with the alternatives available to you. Those steps matter more than the download itself.
Overall, I see DailyPay On-Demand Pay as a focused and potentially useful bridge for eligible workers who have earned money but need access before the usual payday. Its value comes from solving a timing problem, not from creating more income. I would recommend it to a disciplined user facing an occasional cash-flow gap, while steering anyone with a recurring deficit toward broader budgeting, savings, or financial support. Used carefully, it can make an awkward few days easier; used automatically, it can make the following payday harder.
FAQ
What is DailyPay On-Demand Pay and how does it work?
DailyPay On-Demand Pay is an earned wage access service that may let eligible employees access part of their pay before the regular payday. After connecting your employer-supported account, the app shows available earnings based on hours or wages already recorded. You can request a transfer to a linked bank account or supported debit card, while any remaining balance is generally paid through your normal payroll process.
Who can use DailyPay On-Demand Pay?
DailyPay is not available to everyone automatically. Access usually depends on whether your employer offers DailyPay and whether your employment, payroll records, and earnings meet the service’s eligibility requirements. Availability can also vary by work schedule, payroll system, location, and employer settings. If your employer is not a participating organization, downloading the app alone may not provide access to earned wage transfers.
Are there fees for using DailyPay On-Demand Pay?
DailyPay may offer different transfer options, and fees can depend on how quickly you want to receive your money and which delivery method you choose. Standard or slower transfers may have different pricing from instant transfers, while some account features can be free. Before confirming a transaction, carefully review the displayed fee, transfer amount, and final amount you will receive.
How much money can I access before payday?
The amount available through DailyPay is generally based on wages you have already earned, but it may not equal your full paycheck. The app can account for employer rules, payroll deductions, taxes, hours reported, and other adjustments. Your available balance may change during the pay period, and the exact amount can be different from one payday cycle to another.
Will using DailyPay affect my regular paycheck or employment?
Using DailyPay normally means that money transferred early is deducted from the paycheck associated with that pay period, so your scheduled payday deposit may be smaller by the amount already received, along with any applicable fees. It should not change your wage rate or employment status, but you should review your employer’s terms and payroll information to understand how transfers are shown.


